Jewelry Insurance
Your engagement ring, your grandmother's pearls, your favorite watch. The right coverage protects the pieces that matter most, far beyond what a home policy will pay.
Jewelry Insurance in New Mexico and West Texas
Here is something most people never find out until it is too late: your homeowners or renters policy covers stolen jewelry only up to a small limit, usually around 1,500 dollars total. If your engagement ring is worth 8,000 dollars, that gap is on you. And if you simply lose a ring, drop it down the drain, or crack a stone, a standard policy will not pay at all.
Jewelry insurance closes that gap. By scheduling your valuable pieces on a floater or a stand-alone policy, you protect each item at its full appraised value, against far more than theft. As a local independent agency, we help you document what you own and put the right coverage in place, so a lost or damaged piece never turns into a financial loss on top of a personal one.
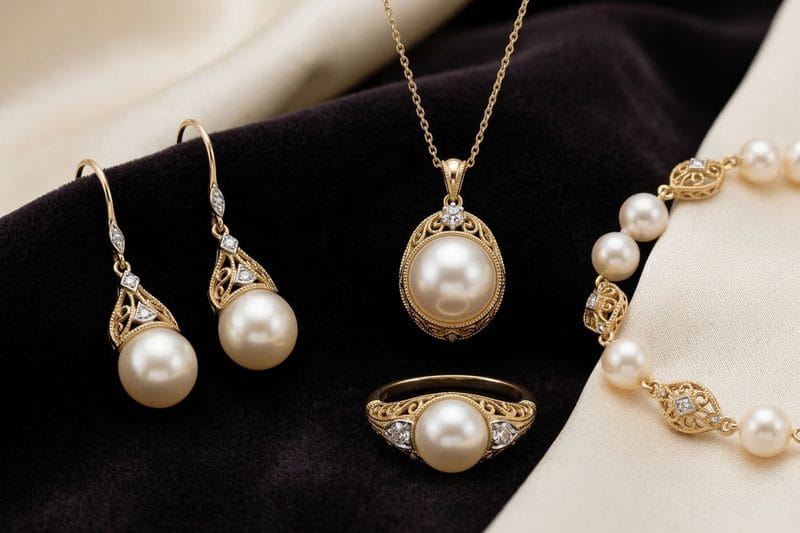
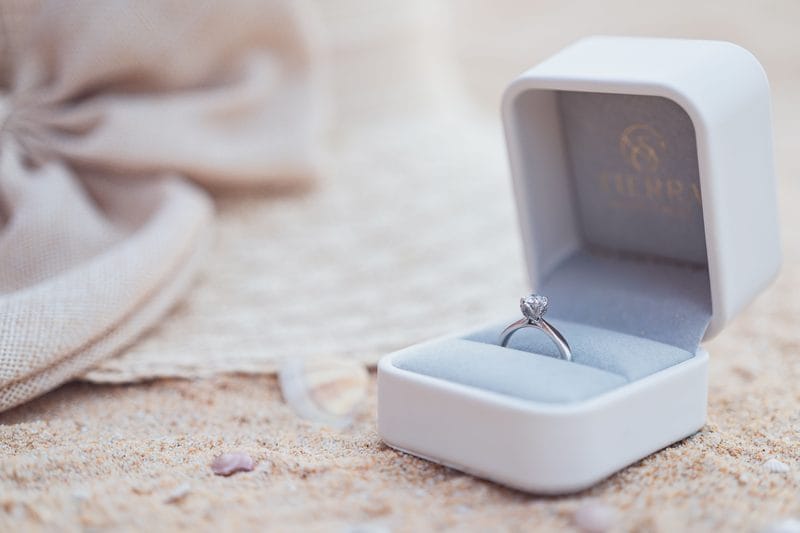
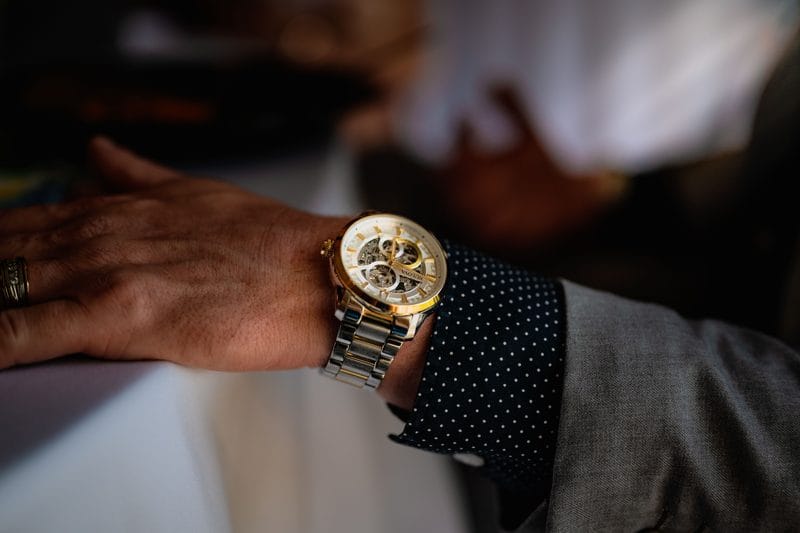
What Jewelry Insurance Covers
Scheduling your pieces protects their full value against the losses a home policy leaves out.
Full Value, Beyond Theft
A scheduled piece is insured at its appraised value, not capped at a small sub-limit, and it is covered for the same perils as your home plus the ones a standard policy leaves out.
Loss and Mysterious Disappearance
This is the big one homeowners will not pay for: dropping a ring down the sink, losing an earring, or a piece that simply goes missing without a trace. A floater covers it.
Accidental Damage
A chipped or cracked stone, a bent band, or a diamond that falls out of its setting are all covered, so an everyday accident does not cost you the whole piece.
Worldwide, Usually No Deductible
Your pieces are protected whether they are being worn, traveling with you, or locked in a safe, and scheduled jewelry typically comes with no deductible to pay at claim time.
How to insure your jewelry the right way
To schedule a valuable piece, you will usually need a recent appraisal or the original bill of sale so the item can be insured at its exact value. Most insurers want an appraisal completed within the last few years, and it is worth updating it periodically, because as gold and diamond prices rise, an old appraisal can leave a treasured piece underinsured. We will walk you through exactly what documentation you need and make it simple.
The best part is how affordable this protection is. Scheduled jewelry coverage generally costs only a small fraction of an item's value each year, so protecting a ring, a watch, or a set of heirloom pieces usually costs far less than people expect. You can add the coverage as a rider on your homeowners or renters policy, or write it as a stand-alone policy, whichever fits your situation best.
A few simple habits make the whole process easier. Keep photos of each piece, store your appraisals and receipts somewhere safe, and let us know whenever you buy or inherit something new so it can be added to your policy right away. If you ever do need to file a claim, that documentation is what turns a stressful loss into a quick, fair replacement.
Whether it is an engagement ring, a family heirloom passed down for generations, a fine watch, or loose gemstones, we can help you protect it. The Insurance Information Institute has a helpful guide to documenting your valuables, which is the first step to insuring them, and from there we can build the right protection around the pieces you love.